
Market Update · 16 min read
The 30-Year Is 7.03%. That Is the Fifth Straight Rise.
Freddie Mac’s September 24, 2026 survey put the 30-year fixed at 7.03% and the 15-year fixed at 6.42%. The 30-year is 8 basis points above last week’s 6.95% print, and it is the first weekly average at or above 7% since January 16, 2025. The dollar figures below are principal and interest on a stated loan. A lock is a written quote.

Freddie Mac’s Primary Mortgage Market Survey released September 24, 2026 put the 30-year fixed-rate mortgage at 7.03%. The 15-year fixed was 6.42%. The 30-year is 8 basis points above the September 17 print of 6.95%. The 15-year is 16 basis points above 6.26%. This release is the September 24 survey; the 6.95 percent figure is last week’s print.
A year earlier, the same survey averaged 6.30% on the 30-year and 5.49% on the 15-year. That is 73 basis points higher on the 30-year and 93 basis points higher on the 15-year than the year-ago week. Freddie Mac’s release states those year-ago comparisons directly. FRED’s matching observations are the September 25, 2025 prints on MORTGAGE30US and MORTGAGE15US.
Sam Khater, Freddie Mac’s chief economist, on the September 24 release: “The housing market remains supported by a solid labor market and an economy that is growing at a healthy rate.” That is the official sentence on the print. A buyer still needs a written quote dated after September 24. The quote starts on the mortgage page.
The survey Freddie describes is conventional, conforming, fully amortizing home-purchase loans for borrowers who put 20 percent down and have excellent credit. It is an average of applications collected through Loan Product Advisor, from 12:00 a.m. Eastern on Thursday through 11:59 p.m. Eastern on Wednesday, published Thursday at noon. Freddie’s 2026 publication calendar dates this one as publication day September 24, week beginning September 17, week ending September 23. FRED stores the same survey with observation date September 24, 2026, weekly, ending Thursday. A calendar that says September 23 and a FRED row that says September 24 are the same release.
This is a national rate briefing for Florida buyers, sellers, and owners. It sits next to last week’s 6.95% survey, the September 10 survey at 6.76%, the September 16 FOMC hike, and the August Census/HUD housing-starts release. For local process, keep the Florida markets page, the Florida home buying guide, and the Citrus, Hernando, Pasco, Hillsborough, and Pinellas overviews in the same reading list.
The six Thursday path
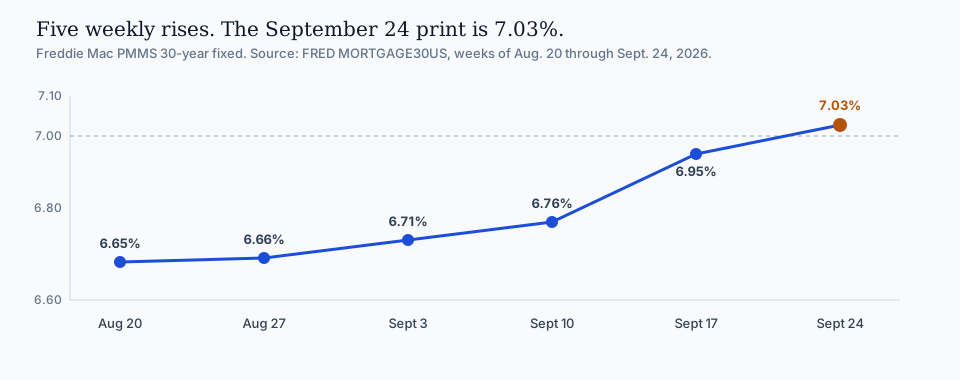
Freddie Mac’s 30-year fixed, on FRED series MORTGAGE30US, for these Thursdays:
- August 13: 6.67%
- August 20: 6.65%
- August 27: 6.66%
- September 3: 6.71%
- September 10: 6.76%
- September 17: 6.95%
- September 24: 7.03%
August 20 was a one-basis-point dip from August 13. Every Thursday since then has been higher. That is five straight weekly increases, from 6.66% on August 27 to 7.03% on September 24. From the August 20 print of 6.65% to this week is 38 basis points. Nineteen of those basis points arrived on September 17. Eight more arrived on September 24.
The 15-year fixed on MORTGAGE15US:
- August 13: 5.96%
- August 20: 5.95%
- August 27: 5.98%
- September 3: 6.04%
- September 10: 6.09%
- September 17: 6.26%
- September 24: 6.42%
The 15-year rose 16 basis points this week, twice the 30-year’s move. The gap between the two products narrowed. On September 17 the 30-year sat 69 basis points above the 15-year (6.95 minus 6.26). On September 24 the gap is 61 basis points (7.03 minus 6.42).
The last time the weekly average was at 7 percent
On MORTGAGE30US, the last weekly print at or above 7.00% before this one was January 16, 2025, at 7.04%. The next week, January 23, 2025, was 6.96%. From January 23, 2025 through September 17, 2026, every weekly 30-year average on that series printed below 7 percent. September 24, 2026, at 7.03%, is the first week back at or above 7 percent. It is also one basis point under the January 16, 2025 print. Crossing 7 percent and matching the old high are two different facts. This week did the first. It did not print a new high versus January 2025.
The 15-year has its own history on MORTGAGE15US. 6.42% is the highest weekly 15-year average since May 2, 2024, when the series printed 6.47%. From May 9, 2024 through September 17, 2026, the highest 15-year print was 6.38%, on May 9, 2024. The January 16, 2025 week, when the 30-year was 7.04%, the 15-year was 6.27%. This week’s 15-year is higher than that January week even though the 30-year is one basis point lower.
What eight basis points does to a payment
The survey average is a rate. A payment is principal, term, and that rate, run through the standard fully amortizing formula. Monthly principal and interest equals the principal, times the monthly rate, times (1 + monthly rate) raised to the number of months, divided by that same power minus one. The monthly rate is the annual rate divided by 12. A 30-year term is 360 months. A 15-year term is 180 months. The figures below use only the printed survey rates. They leave out taxes, insurance, association dues, and any mortgage insurance. They are the arithmetic on Freddie’s average, for a borrower who wants to see the week’s move in dollars. They are a lock only after a lender writes one.
On $300,000 of principal:
- 30-year at 6.95%: $1,985.84 a month
- 30-year at 7.03%: $2,001.96 a month
- Difference: $16.12 a month, or $193.44 over twelve such payments
- 15-year at 6.26%: $2,573.90 a month
- 15-year at 6.42%: $2,600.15 a month
- Difference: $26.25 a month, or $315.00 over twelve payments
On $400,000 of principal:
- 30-year at 6.95%: $2,647.79 a month
- 30-year at 7.03%: $2,669.27 a month
- Difference: $21.48 a month, or $257.76 over twelve payments
- 15-year at 6.26%: $3,431.87 a month
- 15-year at 6.42%: $3,466.86 a month
- Difference: $34.99 a month, or $419.88 over twelve payments
Scaled to a round loan size, the eight-basis-point move on the 30-year is about $5.37 a month per $100,000 of principal. The sixteen-basis-point move on the 15-year is about $8.75 a month per $100,000. A buyer with a different principal can multiply. A $300,000 loan with 20 percent down is a $375,000 purchase price. A $400,000 loan with 20 percent down is a $500,000 purchase price. Those two prices are illustrations so the survey has a dollar figure. They are round numbers chosen for the arithmetic. Freddie’s surveyed borrower is the 20-percent-down profile, which is why the examples use that down payment and skip mortgage insurance.
Last week’s move was larger. Nineteen basis points, from 6.76% on September 10 to 6.95% on September 17, changed the national average more than this week’s eight. A shopper who already reran the payment after September 17 is looking at another $16.12 a month on a $300,000 30-year loan, on top of the jump that was already in last week’s survey. A shopper still holding a July quote is comparing that old quote with 7.03%, not with 6.95%.
The 10-year during the application week
The September 16 FOMC hike set the federal funds target range at 3.75–4.00% on a 12–0 vote, effective September 17. That is the overnight policy rate. This survey is the house rate on purchase applications from September 17 through September 23. The two numbers can be printed in the same week and still describe different markets.
The 10-year Treasury yield is the closer cousin, and it is still a different series. FRED DGS10, the daily constant-maturity close, inside this application window:
- September 17: 4.94%
- September 18: 5.01%
- September 21: 4.96%
- September 22: 4.96%
- September 23: 5.11%
From the September 17 close to the September 23 close, the 10-year rose 17 basis points, from 4.94% to 5.11%. Over the weekly mortgage survey that contains those days, the 30-year rose 8 basis points. The Treasury moved more than the mortgage average across that window. A Florida lock still has to be read off the lender’s quote, not off the 17-basis-point Treasury change.
Other mortgage surveys use other samples and other weeks. The MBA applications briefing covers the week ending September 4, when MBA’s contract 30-year was 6.85%. That print is the week ending September 4, before the September 10, September 17, and September 24 Freddie releases. Daily lock desks move inside Freddie’s Thursday-to-Wednesday window. If a headline says 7.03% and a lender’s screen says something else on Friday, September 25, both can be current for what they measure. The Freddie number is the weekly average. The lender number is the quote. Ask for the quote in writing, with the date on it.
What a Florida buyer and seller do with 7.03%
For a buyer, the useful object is a written quote dated after September 24, on the house you are actually offering on. A pre-approval from July is a credit story. The September 10 survey at 6.76% and the September 17 survey at 6.95% are the path. They are no longer the current weekly average. If the payment at 7.03% does not clear, the funds-rate range will not fill the gap. An adjustable-rate mortgage is a product with a reset date. The MBA briefing is the place to read how ARM share was behaving in early September, before anyone treats that share as advice.
For a first-time buyer, a Florida Housing second mortgage is a different program from this weekly average. The Hometown Heroes 2026 briefing is the occupation and down-payment file. VantageScore 4.0 is the credit-score file. Neither one reprints Thursday’s 7.03%.
For a seller, five rising Thursdays are a reason Saturday traffic can thin while the house is unchanged. Price against current comps and a current quote. The pricing strategy guide is the process. When a lender orders a value, that file is an appraisal. August existing-home sales, already published, were 3.98 million at a seasonally adjusted annual rate, with 1.62 million homes for sale and a 4.9-month supply. This Thursday survey does not rewrite that month. It does change the payment a buyer runs on a listing that is still sitting.
For a new-construction shopper, a builder buydown is a concession with an expiration. Ask what the principal and interest become when the buydown ends, and run that question at 7.03%, not at the teaser. August housing starts are the separate Census construction release, CB26-147: a 1,275,000 seasonally adjusted annual rate. Use that file for how much is being started. Use this file for the survey. The Florida home buying guide is the process either way.
Insurance and flood stay on their own line. Eight basis points do not reprice a roof or a zone. Keep the Pasco flood and insurance guide next to the rate conversation when the house is in a mapped zone. The same paperwork logic shows up in the Hernando flood guide.
Neighborhood files do not change because Thursday’s average moved: South Tampa and Hyde Park, Wesley Chapel, New Tampa, Dunedin, Clearwater. Statewide context stays on Florida markets. Bridge Point’s residential buying and home selling pages are the service layer when the quote has to be run against a specific address. The residential page is the front door.
Citrus files next to a national average
Citrus County has four briefings that a 7.03% survey does not replace. The people-and-schools briefing carries Census QuickFacts at 171,666 on July 1, 2025, the Bureau of Economic and Business Research’s April 1, 2025 estimate of 166,500, and the school district’s 14,845 preliminary projection for 2025–26. The only countywide owner-occupied value already on an official table in that briefing is the Census ACS 2020–2024 median of $245,500. That figure is a multi-year value. It is not a September 2026 sale price, and it is not the principal in the payment examples above. A buyer who multiplies $245,500 by 7.03% and calls the result a Citrus mortgage has mixed a five-year Census value with a one-week national average.
Crystal Ridge is the Lecanto PUD where infrastructure may start: Phase 1 is 234 lots and 10 tracts at 5859 W Crystal Oaks Drive, and Phase 2A is about 213 lots. On the county’s August 18, 2026 applications list, both final plats were still unfiled. A 7.03% survey is the house-rate backdrop for a buyer comparing a resale with a street that is not recorded yet. It does not put a price on an unplatted lot.
Black Diamond Town Center is the commercial subdivision the same county list already places under construction, improvement plans IMP2024-00001 at 3499 W Norvell Bryant Highway, with final plat FPLT2025-00003 still awaiting the applicant’s revisions. A residential survey does not set a pad rent.
The CR-486 interchange map is a comprehensive-plan hearing set for October 26, 2026, at 5:01 p.m. The August 18 list tracks it as CPA-2025-00008. The June 22 minutes track the transmitted draft as CPA-2026-00002. The map is not adopted. A weekly mortgage average does not draw the boundary, and the boundary does not change Thursday’s 7.03%.
Read them as four clocks plus this one. People and schools say who lives in the county. Crystal Ridge says where dirt may start and where a plat is still out. Town Center says which commercial subdivision is already in the ground. The interchange map says what the board is scheduled to consider on October 26. Freddie says what the national purchase-mortgage average was for applications from September 17 through September 23. The Citrus County market overview and the Lecanto home guide are the process files when the address is in that county.
Commercial coupons are a different conversation
A 30-year residential survey is the house payment. A commercial loan is a term sheet on a building, a tenant, and a bank’s current appetite. The July SLOOS briefing is the credit file: banks’ answers on standards and demand for construction, land development, and loans on standing buildings, next to the H.8 loan book. Pasting 7.03% onto a U.S. 19 asking price does not produce a cap rate, because this survey never collected one.
The second-order link is still real. Households that qualify at 7.03% are the same households who rent, who buy a small user building, or who stall. Garden-style, build-to-rent, and small mixed-use feel that. Corridor work stays in the Citrus commercial overview, the Pasco commercial overview, and the Hillsborough commercial overview. Commercial buying is the service layer for a specific building. The commercial page is the front door.
The through-line
The 30-year is 7.03% because the weekly survey rose for a fifth straight Thursday, by 8 basis points, from 6.95% to 7.03%. The 15-year is 6.42%, up 16 basis points from 6.26%. On the FRED history of this survey, 7.03% is the first weekly 30-year at or above 7 percent since January 16, 2025, when the print was 7.04%. A year ago the 30-year was 6.30% and the 15-year was 5.49%. On a $300,000 principal, the week’s move is $16.12 a month on a 30-year and $26.25 a month on a 15-year, principal and interest only. The funds range is still 3.75–4.00%. The 10-year closed at 5.11% on September 23. If you are buying or listing in Hernando, Citrus, Pasco, Hillsborough, or Pinellas, use a written quote dated after September 24 and a current comp. The mortgage page is where that quote starts. The appraisal page is where a lender’s value order starts.
What to watch next
- Next Freddie Mac PMMS: October 1, 2026. The publication calendar sets that release as the week beginning September 24 and ending September 30.
- FHFA House Price Index, July 2026: scheduled for September 29. A repeat-sales index, on its own page when it prints.
- September employment situation: Bureau of Labor Statistics, October 2, 8:30 a.m. Eastern.
- Minutes of the September 15–16 FOMC meeting: October 7.
- September CPI: October 14.
- Next FOMC: October 27–28. That meeting does not include a new Summary of Economic Projections.
Sources: Freddie Mac, Primary Mortgage Market Survey release, September 24, 2026 (30-year fixed 7.03% as of September 24, up from 6.95%; 15-year fixed 6.42%, up from 6.26%; year-ago 6.30% and 5.49%; chief economist Sam Khater’s comment on the labor market and growth; survey scope of conventional, conforming, fully amortizing purchase loans with 20% down and excellent credit), distributed on GlobeNewswire and consistent with the rates on FRED. Freddie Mac PMMS publication calendar for 2026 (September 24 publication; week beginning September 17; week ending September 23; next publication October 1). FRED series MORTGAGE30US and MORTGAGE15US, Freddie Mac via the Federal Reserve Bank of St. Louis, observations from August 13, 2026 through September 24, 2026, plus January 16, 2025 (7.04% and 6.27%), January 23, 2025 (6.96%), May 2, 2024 (15-year 6.47%), May 9, 2024 (15-year 6.38%), and September 25, 2025 (6.30% and 5.49%). FRED series DGS10, Board of Governors H.15, daily closes September 17, 18, 21, 22, and 23, 2026. FOMC statement of September 16, 2026, cited for the 3.75–4.00% funds range. Census/HUD New Residential Construction, August 2026, release CB26-147, cited for the 1,275,000 starts rate. NAR existing-home sales for August 2026, cited for the 3.98 million pace, 1.62 million listings, and 4.9-month supply. MBA Weekly Applications Survey, week ending September 4, 2026, cited for the 6.85% contract rate. Citrus population, school, Crystal Ridge, Black Diamond Town Center, and CR-486 figures are the ones already printed in those briefings.
For help reading this survey against a specific house in Hernando, Citrus, Pasco, Hillsborough, or Pinellas County, contact Bridge Point Business & Real Estate Advisors at 352-515-0226 or request a consultation.
Questions people ask first
Quick answers to common questions about this topic.
What is the Freddie Mac 30-year mortgage rate as of September 24, 2026?
Freddie Mac’s Primary Mortgage Market Survey put the 30-year fixed at 7.03% and the 15-year fixed at 6.42% as of September 24, 2026. The applications in that average ran from Thursday, September 17, through Wednesday, September 23. A lender’s lock can differ.
How much did mortgage rates rise from the 6.95% survey?
The 30-year rose 8 basis points, from 6.95% on September 17 to 7.03% on September 24. The 15-year rose 16 basis points, from 6.26% to 6.42%. It is the fifth straight weekly increase in the 30-year average.
Is 7.03% the first weekly print at or above 7% since 2025?
Yes, on FRED’s MORTGAGE30US series. The previous weekly average at or above 7% was January 16, 2025, at 7.04%. From January 23, 2025 through September 17, 2026, every weekly 30-year print was below 7%. This week’s 7.03% is one basis point under that January 2025 print.
What does 7.03% do to a monthly payment versus 6.95%?
On a $300,000 principal, 30-year principal and interest is $1,985.84 at 6.95% and $2,001.96 at 7.03%, a difference of $16.12 a month. On $400,000 the difference is $21.48 a month. The 15-year difference on $300,000, from 6.26% to 6.42%, is $26.25 a month. Taxes, insurance, and mortgage insurance are not in those figures.
Why does my lender quote a different rate than 7.03%?
Freddie Mac averages a week of conventional purchase applications for borrowers with excellent credit and 20% down. Other surveys and daily lock desks use different samples and different days. MBA’s contract 30-year for the week ending September 4 was 6.85%. Ask for a written quote dated after September 24.
Did the 10-year Treasury rise during this survey week?
FRED DGS10 closed at 4.94% on September 17, 5.01% on September 18, 4.96% on September 21, 4.96% on September 22, and 5.11% on September 23. That is 17 basis points from the first close in the window to the last. The 30-year mortgage average rose 8 basis points over the same week.
Is 7.03% the same thing as the September Fed hike?
No. The September 16 FOMC statement set the federal funds target range at 3.75% to 4.00%. Freddie’s 7.03% is the weekly average on 30-year purchase mortgages for applications from September 17 through September 23. One is overnight bank policy. The other is a house-loan survey.
Does 7.03% set a Citrus County home price?
No. It is a national mortgage average. Citrus population, the Crystal Ridge plats, Black Diamond Town Center, and the October 26 CR-486 hearing are separate county files. The ACS 2020–2024 median owner-occupied value of $245,500 is a multi-year Census figure, not a September sale price and not a loan amount.
Should a Florida buyer wait for the next survey?
The next official PMMS is October 1, 2026. Waiting is a bet on that print. A written quote dated after September 24, on a house that clears the payment, is a plan you can act on this week.
Who can help apply this rate to a Florida house?
Bridge Point Business & Real Estate Advisors advises buyers and sellers across Hernando, Citrus, Pasco, Hillsborough, and Pinellas. Call 352-515-0226 or request a consultation.
Talk with Bridge Point
Considering a purchase or sale in this market? Local guidance can make a meaningful difference.
Schedule a consultation
