
Home Buying · 17 min read
Florida Hometown Heroes Is Broader Than “Teacher or Sheriff.” Here Is Who It Is For.
The 2026 Hometown Heroes test starts with the employer, not the badge. eHousingPlus still showed over $25 million in DPA on September 16. That is leftover from the $50 million pot — not a new 2027 check.

Florida Hometown Heroes is not a medal for one job title. The 2026 program starts with the employer. A cafeteria worker paid by a K–12 school can qualify. A civilian employee of a sheriff’s office can qualify. A teacher at the same school and a sworn deputy at the same office can too. A district-office desk, a college job, a fully remote title, and a private security badge cannot.
The program is run by the Florida Housing Finance Corporation. For 2026 it is limited to people employed full-time by a Florida-based employer as a health-care worker, school staff member, first responder, public safety or court employee, or child-care worker; to U.S. military, Coast Guard, reserve, and Florida National Guard service members; and to veterans employed full-time by a Florida-based employer. That list is in Florida Statute 420.5096. The lender guide tells originators to start with the employer, not the borrower’s job title.
This is a financing briefing for first-time buyers on our streets, not a closed-sale count. Keep it next to the Florida home buying guide and the Hillsborough, Pasco, and Pinellas overviews. A Hometown Heroes lock does not set a South Tampa list price. It can change who still clears the down payment on a house they already liked.
What the assistance actually is
Eligible buyers can get a 30-year fixed first mortgage — FHA, VA, USDA-RD, or Freddie Mac HFA Advantage — with no origination points and no discount points. Florida Housing sets the rate daily in the reservation system. Lenders may not charge the old 1% origination fee on this product.
The down-payment and closing-cost help is a second mortgage equal to 5% of the first-mortgage amount, with a $10,000 minimum and a $35,000 maximum. A first mortgage of $200,000 or less receives the $10,000 floor. The second is 0%, non-amortizing, and deferred for 30 years. It is not forgiven. The balance comes due in full on sale, refinance, payoff of the first, transfer of the deed, or if the buyer stops living in the house as a primary residence. Those repayments go back into the program.
Hometown Heroes cannot be stacked with Florida Housing’s other down-payment products. Other agencies can sit in third position. Realtor commission cannot be paid with Hometown Heroes funds. Purchases only. Refinances are out.
How much money is left, and does 2027 get a new pot
The 2026 down-payment pool is still open. It is not unlimited.
Florida Housing’s administrator, eHousingPlus, posted the September 16, 2026 rate sheet as “Over $25 Million Available in Hometown Heroes 2026 DPA.” That is a floor, not a penny count. There is no public live ticker. Lenders reserve against a fully executed purchase contract, first come, first served. You may not switch an existing Florida Housing reservation onto Hometown Heroes.
That leftover sits inside a $50 million nonrecurring appropriation. The 2025–26 round of the same size opened August 18, 2025, and Florida Housing said it was fully committed by late February 2026 — a little over 3,000 families in six months. The current $50 million reopened July 13, 2026. The 2026–27 budget carried any unspent balance of that appropriation into fiscal year 2026–27, which ends June 30, 2027. If this pot still has money in January, reservations can continue from the same $50 million. That is not a second $50 million labeled 2027.
Florida Statute 420.5096 says the program is intended to be evergreen, and that repayments stay in the program for more loans. That keeps Hometown Heroes alive on paper. It does not write a new legislative check for July 2027 and after. Earlier years ran $100 million and $150 million pots. This year’s appropriation is smaller. A participating lender can see today’s reservation capacity in eHousingPlus. Pre-approval does not lock the second mortgage. The contract lock does.
Start with the employer, not the title
The August 19, 2026 employer checklist is blunt: start with the employer, not the job title. The borrower must work full-time for a Florida-based employer in an eligible category, at a brick-and-mortar Florida location. Only one occupying borrower has to meet that test. A co-signer cannot supply it. An offer letter is not enough. Employment has to be current at closing.
“Full-time” is whatever that employer calls full-time. Hybrid workers can qualify if they report to the physical location at least three days a week. Fully remote workers cannot. The 2026 guide’s shorthand is frontline workforce, not a laptop in another state.
The example job lists are not all-inclusive. Any full-time employee paid directly by a qualifying employer may be eligible. A title does not rescue an ineligible employer. A medical-billing office, a school-district headquarters, a private law firm, and a college are still out even if the borrower’s business card sounds like a Hometown Hero.

A school is the cafeteria line, not just the classroom
Borrowers employed full-time by a Florida K–12 public, private, charter, or magnet school are eligible. The official examples include classroom teachers, teacher aides, principals and assistant principals, counselors, career specialists, librarians and media specialists, school psychologists, social workers, food-service and cafeteria staff, and maintenance and janitorial staff. Florida Virtual School teachers qualify when the paystub or verification of employment shows they are paid directly by Florida Virtual School.
Those examples are not a closed list. A full-time coach on that school’s payroll, working at that K–12 campus, is the same employer test as the cafeteria worker. A stipend-only season, a booster-club check, or a job paid by someone other than the school is not.
The hard stop is the building. A borrower employed by a school-district administrative office does not qualify. A college or university employee does not qualify. The paystub or verification of employment has to name the specific K–12 school that pays the borrower and the Florida address where that person works.
A sheriff’s office is the department, not only the sheriff
Public-safety eligibility is a Florida-based local, county, state, or federal law-enforcement department, a juvenile-detention facility, a correctional facility, or an emergency-operations center. A county sheriff’s office is a county law-enforcement department. The official examples include sworn law-enforcement officers, 911 public-safety communicators, correctional officers, correctional probation officers, and juvenile detention and probation officers.
Those examples are not all-inclusive. A records clerk, evidence technician, or other civilian employee paid by that sheriff’s office and working at that department is the same employer test as the deputy. The badge is not the test. The payroll and the location are.
TSA agents, private security staff, contractors, and public-works employees — water-treatment workers are the guide’s example — do not qualify just because the work feels like public safety. Lifeguards, safety or security staff, and emergency contractors do not qualify unless they are employed, paid by, and working at a Florida fire department, ambulance service, or hospital.
Healthcare is the patient-care building
Borrowers employed full-time by a Florida healthcare provider or physician, hospital, assisted-living facility, mental-health facility, or other healthcare facility are eligible. Official examples run from registered nurses, LPNs, CNAs, and physicians through technicians, therapists, pharmacists, dental staff, medical assistants, and patient transporters. The list is not closed. The facility has to provide direct patient care.
A medical-billing office, a supply or manufacturing company, or a corporate headquarters does not qualify. The paystub has to name the specific Florida medical facility that pays the borrower and where that person physically works.
Fire, ambulance, courts, and child care
First responders in this program are people employed full-time by a Florida fire department, ambulance service, or hospital. The examples are firefighters, certified EMTs, and certified paramedics.
Court employees are people employed full-time by a Florida county, state, or federal court, a court administrator’s office, a State Attorney’s Office, or a Public Defender’s Office. Examples include assistant state attorneys, assistant public defenders, court clerks, and court stenographers employed by the Florida Supreme Court, a district court of appeal, a circuit court, or a county court. Private law firms and contract legal shops are out.
Child-care eligibility is any worker at a Florida licensed child-care facility, or at a licensed or registered home day care, under the licensing and exemption rules in Chapter 402 of the Florida Statutes. The August 2026 checklist also expects a Gold Seal, VPK, Head Start, or School Readiness designation, verified through the Department of Children and Families provider search.
Military and veterans are a different door
Active-duty members of the U.S. armed forces qualify with a Leave and Earnings Statement. They do not have to work for one of the civilian employer categories above.
Reserve members, including the Florida National Guard, and veterans must work full-time for any Florida-based employer. That employer does not have to be a school, hospital, or sheriff’s office. The guide’s examples are ordinary Florida employers such as a retailer. Veterans are not excused from the full-time rule. Discharge has to be other than dishonorable. An eligible surviving spouse with a VA certificate of eligibility can use the veterans first-time-buyer exemption only on the Hometown Heroes TBA option with VA financing, and still has to meet the other program tests, including current full-time work for an eligible Florida employer.
Who still has to clear the rest of the box
Occupation is one gate. The rest of the 2026 TBA file still applies.
- Primary residence in Florida. The buyer intends to occupy within 60 days of closing.
- First-time buyer, unless an exemption applies. No ownership interest in a principal residence in the three years before the note is signed. Veterans, active-duty service members, and members of the Reserves or National Guard with a current LES are exempt. Buyers in a federally designated targeted area are exempt. Targeted tracts in our service area are listed in the TBA guide — selected census tracts in Hillsborough, Pinellas, Pasco, Hernando, and Citrus — and the lender checks the address, not a nickname.
- Income and loan caps for the county where the house sits. TBA uses the credit-qualifying income of the borrowers on the loan, including overtime, bonus, and commission that the automated underwrite can use. Bond is a separate reservation path with household income and a lower table.
- Minimum 640 credit score on all loan types. Manual underwrites need 660 and a 43% debt-to-income cap. Automated underwrites can go to 50% DTI. Manufactured housing has its own overlay.
- Homebuyer education for one occupying borrower, completed before purchase, meeting HUD or National Industry Standards. Certificates last two years. Veterans, active-duty, Reserve, and National Guard buyers skip the class unless they use HFA Advantage.
- One-time participation in Florida Housing homebuyer programs. Anyone who previously signed a Florida Housing note or appeared on a Florida Housing deed is done, even if they never lived in that house.
- Certification that the borrower has not been convicted of a sex offense against a minor, as defined in 34 U.S.C. § 20911.
Self-employed borrowers have extra paper. A 1099 contractor has to work full-time for one 1099 employer and report to a specific Florida location of that employer. If the business itself is paid, there has to be a Florida brick-and-mortar place where the borrower provides services. A letter that only says “I work full-time” is not enough.
The 2026 numbers on our streets
Florida Housing’s TBA income and loan-limit table, effective with reservations on or after May 6, 2026, is the figure a participating lender will lock against. For FHA, VA, and HFA Advantage income:
- Hillsborough, Pinellas, Pasco, and Hernando: $172,050
- Citrus: $148,050
USDA-RD uses a separate income cap of $119,850 in those counties. The FHA first-mortgage cap is $541,287. HFA Advantage and VA first mortgages cap at $832,750. Bond reservations use a lower household-income table and a purchase-price cap. Do not mix the two files.
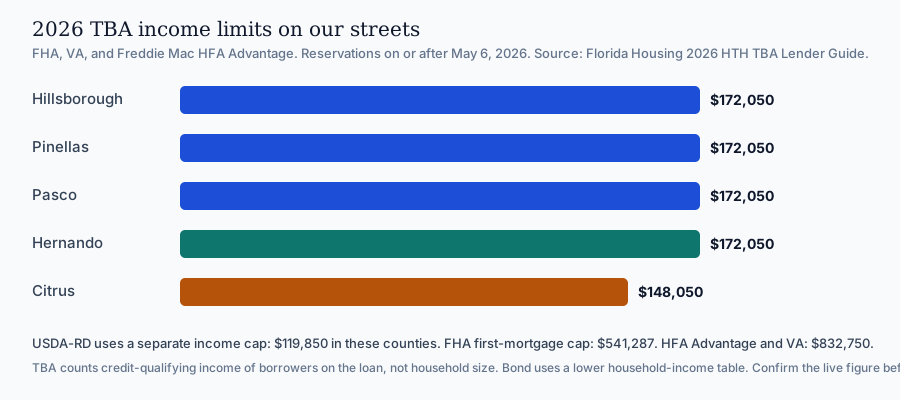
Those caps move. The lender confirms the live number in eHousingPlus before lock. One dollar over the applicable limit is a no.
How a buyer actually starts
Hometown Heroes is reserved by a Florida Housing participating lender. Florida Housing’s site has the lender and real-estate-agent locator. There is no fee to apply for the down-payment assistance. Anyone who asks for an upfront fee to “get you in” is running a scam. Florida Housing’s Inspector General is at 850-488-4197.
The useful first conversation is still the house and the payment, not the acronym. Insurance, flood, HOA or CDD, and the lock quote sit next to the second-mortgage terms. Read the Pasco flood and insurance guide if water is on the search. Keep the street file in Wesley Chapel, New Tampa, South Tampa, Apollo Beach and Ruskin, Dunedin, or Clearwater.
What it does for a buyer and a seller
For a buyer, this program can close a cash-to-close gap that a 6% handle on the 30-year would otherwise leave open. It does not erase credit, insurance, or appraisal. The second mortgage is real debt. It is cheap debt — 0%, no monthly payment — and it is due when the house is sold or refinanced. Ask the lender, in writing, which reservation you are in, TBA or Bond, what income they are counting, and what the second-mortgage payoff looks like if you sell in year five.
For a seller, a Hometown Heroes buyer is not a weaker file by default. It is a first-time, income-capped purchase with a state second behind an FHA, VA, USDA, or HFA first. The appraisal and the insurance binder still decide the week. Price against current comps, not against the assistance amount. The pricing strategy guide is the listing process.
The through-line
The 2026 Hometown Heroes program is for people who work full-time at a qualifying Florida employer — a K–12 school, a healthcare facility that treats patients, a fire or ambulance service, a law-enforcement department including a sheriff’s office, a court or prosecutor or public-defender office, or a licensed child-care facility — plus service members and veterans. The cafeteria line and the civilian sheriff-office desk are in that file when the school or the department is the employer. The district office, the university, the billing company, and the fully remote title are not. Assistance is 5% of the first mortgage, $10,000 to $35,000, at 0%, deferred, and not forgiven. Hillsborough, Pinellas, Pasco, and Hernando TBA income is $172,050. Citrus is $148,050. eHousingPlus still showed over $25 million in the $50 million pot on September 16. That leftover can run through June 30, 2027. It is not a new 2027 check. Confirm the employer, the hours, the live income table, and today’s reservation capacity with a participating lender before you write the offer.
Bridge Point’s residential buying page is where that gets asked against a specific property.
What to watch next
- Remaining DPA on the eHousingPlus rate sheet. The September 16 print said over $25 million. That number moves with every reservation.
- Live income and loan limits in the Florida Housing TBA reservation system. The table here is the May 6, 2026 print.
- Daily first-mortgage rate in eHousingPlus. It is not Freddie Mac’s weekly survey.
- Employer documentation. Paystubs or a verification of employment that name the Florida facility and the hours. Hybrid workers need the three-day onsite test.
Sources: Florida Housing Finance Corporation, Hometown Heroes Program page; Florida Housing press release, February 28, 2026 (2025–26 $50 million fully committed); Florida Statute 420.5096; Florida Housing / eHousingPlus program highlights rate sheet, September 16, 2026; Florida Housing / eHousingPlus HTH Eligible Employer Reference Guide (August 19, 2026); Florida Housing 2026 Hometown Heroes TBA Lender Guide (Lakeview, revised August 14, 2026), including the income and loan-limit table effective May 6, 2026, and the eligible-employer pages; Florida Housing Bond-versus-TBA cheat sheet (August 21, 2026); Florida Association of Counties summary of the SFY 2026–27 General Appropriations Act ($50 million Hometown Heroes appropriation, unexpended balance reappropriated through June 30, 2027).
For help reading this against a specific house in Hernando, Citrus, Pasco, Hillsborough, or Pinellas County, contact Bridge Point Business & Real Estate Advisors at 352-515-0226 or request a consultation.
Questions people ask first
Quick answers to common questions about this topic.
Does a cafeteria worker or janitor at a Florida school qualify?
Yes, when they are full-time employees paid by a Florida K–12 public, private, charter, or magnet school and they work at that school. Food-service, cafeteria, maintenance, and janitorial staff are on the official example list. A school-district administrative office or a college job does not qualify.
Does everyone at a sheriff’s department qualify, or only the sheriff?
The 2026 test is the department, not the elected title. A county sheriff’s office is a qualifying law-enforcement employer. Sworn officers, 911 dispatchers, and correctional staff are on the example list. Other full-time employees paid by that office and working there can meet the same employer test. TSA, private security, and contractors do not.
Does a school coach qualify?
A full-time coach on the K–12 school’s payroll, working at that school, is the same employer test as other school staff. The official examples are not a closed list. A stipend-only, seasonal, or booster-club paycheck is not the school as employer.
How much down-payment help is it?
Five percent of the first mortgage, with a $10,000 minimum and a $35,000 maximum, as a 0% deferred 30-year second mortgage. It is not forgiven. It is due on sale, refinance, payoff of the first, transfer, or if the buyer stops occupying the home.
What is the 2026 income limit in Hillsborough, Pinellas, and Pasco?
On the TBA table effective May 6, 2026, Hillsborough, Pinellas, Pasco, and Hernando are $172,050. Citrus is $148,050. Those figures are credit-qualifying income of the borrowers on the loan. USDA-RD uses $119,850. Bond uses a lower household-income table. The lender confirms the live number before lock.
How much Hometown Heroes money is left in 2026?
eHousingPlus posted “Over $25 Million Available in Hometown Heroes 2026 DPA” on the September 16, 2026 rate sheet. That is leftover from the $50 million pot that reopened July 13, 2026. There is no public live ticker. A participating lender confirms today’s reservation capacity. Pre-approval does not lock the funds.
Will Hometown Heroes still be available in 2027?
Leftover dollars from the current $50 million can legally be reserved through June 30, 2027. That is the same pot, not a new 2027 appropriation. The statute says the program is meant to be evergreen and that repayments stay in the program. A new check for July 2027 and after has not been enacted.
Who can help apply this to a Florida purchase?
A Florida Housing participating lender reserves the loan. Bridge Point Business & Real Estate Advisors can read the house, the insurance, and the payment against that file in Hernando, Citrus, Pasco, Hillsborough, and Pinellas. Call 352-515-0226 or request a consultation.
Talk with Bridge Point
Considering a purchase or sale in this market? Local guidance can make a meaningful difference.
Schedule a consultation
