
Market Update · 16 min read
New-Home Sales Were 676,000. U.S. House Prices Rose 2.4% From a Year Earlier.
Three official releases landed October 27, 2026. Census and HUD’s September new-home sales file, CB26-174, put sales at a 676,000 seasonally adjusted annual rate, with 476,000 houses for sale and an 8.4-month supply. FHFA’s seasonally adjusted purchase-only House Price Index rose 0.3 percent in August and 2.4 percent from August 2025. S&P Cotality Case-Shiller’s national index rose 2.1 percent over the year; Miami rose 4.2 percent and Tampa fell 0.4 percent.

Three official housing releases landed on October 27, 2026. Census and HUD’s September new-home sales release, CB26-174, put sales of new single-family houses at a seasonally adjusted annual rate of 676,000. FHFA’s seasonally adjusted purchase-only House Price Index rose 0.3 percent from July to August and 2.4 percent from August 2025 to August 2026. S&P Dow Jones Indices published the August S&P Cotality Case-Shiller results the same morning: the national home-price index rose 2.1 percent over the year, Miami rose 4.2 percent, and Tampa fell 0.4 percent.
Those are three different machines. CB26-174 counts new-home contracts — a deposit taken or a sales agreement signed. The FHFA index follows the same single-family houses when they sell again on Fannie Mae and Freddie Mac purchase mortgages. Case-Shiller is a separate repeat-sales index for single-family homes, with metro readings for Miami and Tampa. Read the labels. Do not mash the three into one Florida median.
Financing context for the same week sits on Freddie Mac’s October 22 survey: 7.32 percent on the 30-year fixed and 6.68 percent on the 15-year. Construction volume is the separate September housing-starts file. Resale pace and shelter inflation sit on the September CPI, FOMC minutes, and existing-home sales briefing. Statewide purchase and sale work stays on residential, and the market map stays on Florida markets.
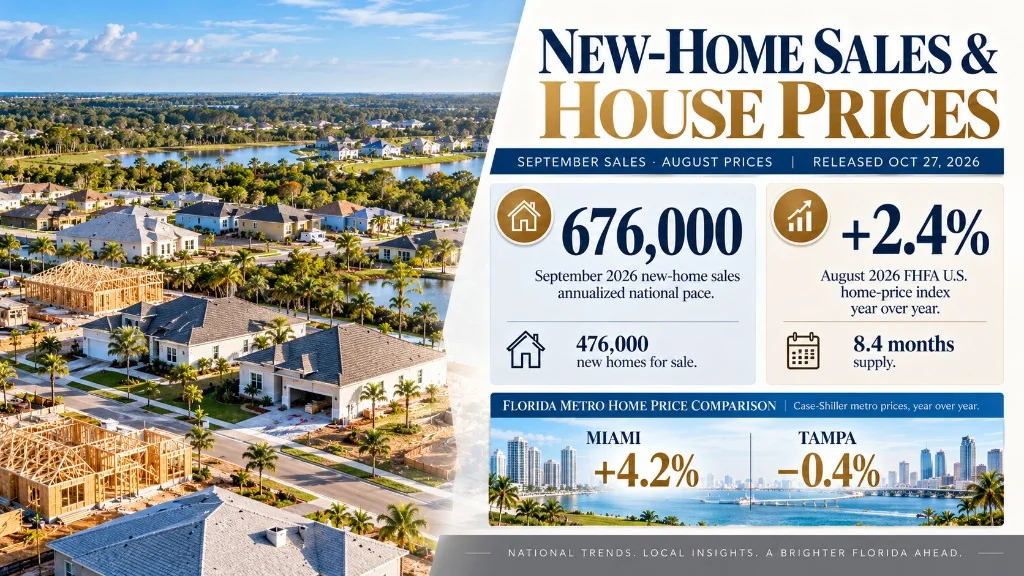
Census and HUD: September new-home sales, CB26-174
Sales of new single-family houses in September 2026 were at a seasonally adjusted annual rate of 676,000, according to the joint Census Bureau and HUD release published October 27 at 10:00 a.m. Eastern. That is 0.6 percent (±13.8 percent) below the revised August rate of 680,000, and 5.3 percent (±12.5 percent) below the September 2025 rate of 714,000. Census marked both national sales moves with an asterisk. The 90 percent confidence interval includes zero, so the Bureau does not have enough evidence to say the actual change differed from zero.
The prior August briefing on this site carried the first August print of 684,000. This release revises August to 680,000 and revises July to 647,000. Preliminary sales estimates are revised about 6.7 percent on average. Treat 676,000 as the first official September print, with that revision habit attached.
The September sales scoreboard
From the joint release and Table 1a, seasonally adjusted:
- Houses sold: 676,000 annual rate. August revised 680,000. September 2025 714,000.
- Houses for sale: 476,000. August revised 481,000. September 2025 487,000.
- Months’ supply: 8.4. August 8.5. September 2025 8.2.
- Median sales price: $400,400. August revised $385,400. September 2025 $416,800.
- Average sales price: $472,800. August revised $470,800. September 2025 $506,800.
The not-seasonally-adjusted count for the month itself was 56,000 houses sold, against 57,000 in August and 58,000 in September 2025. Year to date through September, not seasonally adjusted, the United States sold 506,000 new houses against 521,000 in the same months of 2025, a change of 2.9 percent (±4.8 percent). That year-to-date interval includes zero.
Inventory cleared the monthly test
The seasonally adjusted estimate of new houses for sale at the end of September was 476,000. That is 1.0 percent (±0.9 percent) below the August estimate of 481,000. The interval does not include zero. The year-ago comparison, 2.3 percent (±4.0 percent) below September 2025’s 487,000, still does.
Months’ supply was 8.4 at the current sales rate — 1.2 percent (±14.7 percent) below August’s 8.5 and 2.4 percent (±14.1 percent) above September 2025’s 8.2. Both supply comparisons carry asterisks.
Table 3a splits the seasonally adjusted stock by stage at the end of September:
- Not started: 115,000, against 112,000 in August and 103,000 in September 2025.
- Under construction: 250,000, against 257,000 in August and 262,000 in September 2025.
- Completed: 111,000, against 112,000 in August and 122,000 in September 2025.
Completed homes are 111,000 of the 476,000 for sale. Under-construction homes remain the largest slice. Not seasonally adjusted, the median number of months for sale since completion was 3.0 in September, against 3.1 in August and 2.4 in September 2025.
The average price is the year-ago comparison that cleared
The median sales price of new houses sold in September was $400,400, 3.9 percent (±6.2 percent) above August’s revised $385,400 and 3.9 percent (±8.9 percent) below September 2025’s $416,800. Both median intervals include zero.
The average sales price was $472,800, 0.4 percent (±6.1 percent) above August’s revised $470,800 and 6.7 percent (±6.6 percent) below September 2025’s $506,800. The month-to-month average move includes zero. The year-ago average drop does not. That is the same pattern the August sales briefing carried on the earlier print: the average’s year-ago comparison is the national price line whose interval stays below zero.
September’s 56,000 not-seasonally-adjusted sales, by price band:
- Under $300,000: 11,000, 20 percent.
- $300,000 to $399,999: 17,000, 31 percent.
- $400,000 to $499,999: 10,000, 19 percent.
- $500,000 to $599,999: 7,000, 13 percent.
- $600,000 to $799,999: 5,000, 10 percent.
- $800,000 to $999,999: 2,000, 4 percent.
- $1,000,000 and over: 2,000, 4 percent.
Census’s price note still applies. Changes in sales price reflect mix — region, size, and the rest — and changes in the prices of houses with the same characteristics. The table prints the mix. It does not separate how much of the 6.7 percent average drop was mix and how much was the price of a similar house.
The South printed 413,000
Florida sits inside the South region. South sales in September were 413,000 at a seasonally adjusted annual rate, against revised August 442,000 and September 2025 416,000. The monthly change is 6.6 percent (±17.0 percent) lower. The yearly change is 0.7 percent (±16.9 percent) lower. Both intervals include zero. Divide 413,000 by the national 676,000 and the South is about 61 percent of the national pace. That share is arithmetic on the two printed rates.
Not seasonally adjusted, the South sold 34,000 houses in September, against 38,000 in August and 34,000 in September 2025. South houses for sale, not seasonally adjusted, were 287,000, against 292,000 in August and 303,000 in September 2025. The release does not print a Florida or Citrus sales count.
The other regions on Table 1a: Northeast 32,000, Midwest 89,000, West 142,000. The West’s year-ago print is 17.4 percent (±29.0 percent) below September 2025’s 172,000; that interval includes zero. A Nature Coast buyer is not the West’s year-ago column and is not a blended regional median.
FHFA: August House Price Index
U.S. house prices rose 0.3 percent in August and 2.4 percent from August 2025 to August 2026 on FHFA’s seasonally adjusted monthly purchase-only House Price Index, published October 27, 2026. The previously reported 0.3 percent July increase was revised down to 0.2 percent. The U.S. seasonally adjusted index stood at 444.6 in August, with January 1991 equal to 100, up from 443.2 in July and 434.0 in August 2025.
FHFA titles the workbook for the publication month. The prices in this file are August. The July briefing remains the prior monthly tape. Florida’s state figure is still quarterly through the second quarter of 2026 in the August 25 quarterly report. This monthly release does not replace that state file.
What the index measures
The flagship FHFA HPI is a weighted repeat-sales index. It follows the same single-family houses across purchase transactions financed with mortgages acquired by Fannie Mae and Freddie Mac. A 2.4 percent rise is a rise in the price of those houses. It is not a median sale price, and the workbook’s nominal label means it is not already net of consumer inflation.
For the nine census divisions, seasonally adjusted monthly changes ranged from −0.8 percent in the New England division to +2.1 percent in the East South Central division. Twelve-month changes ranged from +0.5 percent in the Mountain division to +4.4 percent in the East North Central division.
South Atlantic, the division that includes Florida
The South Atlantic census division is Delaware, Maryland, the District of Columbia, Virginia, West Virginia, North Carolina, South Carolina, Georgia, and Florida. On the seasonally adjusted purchase-only series, the division’s August index was 467.6, against 467.9 in July and 461.5 in August 2025 — about 0.1 percent lower on the month and about 1.3 percent higher on the year. The national month was a gain. The Florida-containing division’s month was a slight decline. Both year-over-year prints stayed positive.
A 1.3 percent South Atlantic year is not a Hernando year, a Citrus year, or a Pinellas year. It is the division. A closed sale on a street in Brooksville, Lecanto, Wesley Chapel, Tampa, or Clearwater is a third number — the price on that contract.
Case-Shiller: August national, Miami, and Tampa
S&P Dow Jones Indices released the August 2026 S&P Cotality Case-Shiller results on October 27. The U.S. National Home Price Index, not seasonally adjusted, rose 2.1 percent over the year, up from a 1.9 percent rise in the prior month. The 10-City Composite rose 3.6 percent over the year. The 20-City Composite rose 2.7 percent.
Month to month, before seasonal adjustment, the national index fell 0.2 percent. After seasonal adjustment it rose 0.3 percent. S&P’s analysis notes that consumer prices rose 3.4 percent over the same year, so the national home-price gain was still below that inflation print.
Chicago led the reported metros at +6.7 percent year over year. New York rose 6.2 percent. Cleveland rose 4.3 percent. Seattle fell 2.0 percent. Las Vegas fell 1.3 percent. Denver fell 0.8 percent. Detroit had no valid August update because of Wayne County recording delays; S&P published a July update for that metro instead.
Florida’s two Case-Shiller metros
Miami and Tampa are the Florida metros in the 20-city set.
- Miami: August index 454.69, up 4.2 percent from a year earlier. Month to month, not seasonally adjusted, Miami rose 0.17 percent; seasonally adjusted, it rose 0.23 percent.
- Tampa: August index 372.60, down 0.4 percent from a year earlier. Month to month, not seasonally adjusted, Tampa fell 0.37 percent; seasonally adjusted, it fell 0.07 percent.
Those are metro repeat-sales indexes. They are not a Spring Hill median, a Homosassa median, or a Clearwater condo price. Case-Shiller reflects a three-month moving average of closings, so the August reading includes June and July sales. A Nature Coast offer is still the contract on that house.
How the three tapes sit next to starts, resales, and the 7.32 percent survey
September housing starts, CB26-162, put privately owned housing starts at a 1,221,000 seasonally adjusted annual rate. Single-family starts were 859,000. A start is ground broken. A sale in CB26-174 is a contract. The 676,000 sales pace and the 859,000 single-family starts pace can both be true because they are not the same event.
NAR’s September existing-home sales, already briefed with the September CPI and FOMC minutes, were a 3.99 million seasonally adjusted annual rate, with 1.60 million homes for sale and a 4.8-month supply. New homes in this sales release are a 676,000 pace with 476,000 for sale and an 8.4-month supply. Adding 4.8 and 8.4 does not produce a combined months’ supply.
The mortgage survey is a third clock. Freddie Mac’s October 22 print put the 30-year at 7.32 percent and the 15-year at 6.68 percent. On $300,000, principal and interest is $2,060.79 a month on the 30-year and $2,643.10 on the 15-year, before taxes, insurance, and dues. September contracts in CB26-174 were signed in September. A shopper this week needs a written quote dated after October 22. The quote starts on the mortgage page.
The federal funds target range after the September 16 FOMC hike remains 3.75–4.00 percent. The Committee meets October 27–28, with the statement due at 2:00 p.m. Eastern on October 28. That statement is a separate file from these three morning releases.
What a Florida buyer and seller do with this tape
For a buyer shopping a new house, ask which stage the house is in. Nationally, the September sales rate was 82,000 not started, 214,000 under construction, and 380,000 completed. Ask what the payment becomes when any builder buydown ends, and run that question at a written quote after the 7.32 percent survey. The Florida home buying guide is the process. Residential buying is where a specific address gets read against the quote.
For a resale buyer, an 8.4-month new-home supply is future competition where builders are delivering finished houses, and a longer wait where the stock is still a slab. Completed new homes for sale were 111,000 nationwide. Existing inventory is the NAR file. Shop the house that clears today’s payment. Miami’s 4.2 percent Case-Shiller year and Tampa’s 0.4 percent decline are metro backdrop. They do not set the offer on a Hernando or Citrus street.
For a seller, the national new-home pace and the two price indexes do not reprice the listing by themselves. Price against current comps and a current quote. The pricing strategy guide is that process. When a lender orders a value, the file is an appraisal. A longer new-home supply can pull some weekend traffic toward a builder incentive. It does not repair an asking price the comps do not support.
Insurance and flood stay on their own line. Keep the Pasco flood and insurance guide and the Hernando flood guide next to the conversation when the house is in a mapped zone. Neighborhood process files stay on their own pages: Wesley Chapel, Lecanto, Clearwater, and the Citrus, Hernando, Pasco, Hillsborough, and Pinellas overviews.
The through-line
September new-home sales printed at 676,000 because that is the seasonally adjusted annual rate in CB26-174. The 0.6 percent decline from revised August 680,000 sits inside a ±13.8 percent interval. Inventory fell to 476,000, and the 1.0 percent monthly drop cleared its ±0.9 percent interval. Months’ supply was 8.4. The median price was $400,400. The average was $472,800, and the 6.7 percent drop from September 2025 is the national new-home price comparison whose interval does not include zero. The South was 413,000.
FHFA’s August purchase-only index rose 0.3 percent on the month and 2.4 percent on the year. July’s U.S. change was revised to 0.2 percent. The South Atlantic division, including Florida, was about 0.1 percent lower on the month and about 1.3 percent higher on the year.
Case-Shiller’s national index rose 2.1 percent over the year. Miami rose 4.2 percent. Tampa fell 0.4 percent. The 30-year survey dated October 22 is 7.32 percent. If you are buying, listing, or walking a still-building street in Hernando, Citrus, Pasco, Hillsborough, or Pinellas, use the stage of the house, a written quote dated after October 22, and a current comp. The mortgage page is where that quote starts. The appraisal page is where a lender’s value order starts.
What to watch next
- October FOMC statement: Wednesday, October 28, 2026, 2:00 p.m. Eastern. No new Summary of Economic Projections at this meeting.
- Next Freddie Mac PMMS: Thursday, October 29, 2026.
- October new-home sales: Census and HUD, November 25, 2026.
- FHFA House Price Index through September, with Q3 quarterly data: November 24, 2026.
- Next Case-Shiller release: last Tuesday of November, covering September 2026.
Sources: U.S. Census Bureau and U.S. Department of Housing and Urban Development, Monthly New Residential Sales, September 2026, release CB26-174, October 27, 2026, 10:00 a.m. Eastern, including the public summary and Tables 1a, 1b, 2a, 2b, 3a, and 3b (sales 676,000; August revised 680,000; September 2025 714,000; for sale 476,000; months’ supply 8.4; median $400,400; average $472,800; regional sales; price bands; stage of construction; median months for sale since completion 3.0; year-to-date counts; confidence intervals and the asterisk rule; the statement that preliminary sales are revised about 6.7 percent on average; the definition of a sale as a deposit or a signed agreement). U.S. Federal Housing Finance Agency, news release “FHFA House Price Index Up 0.3 Percent in August; Up 2.4 Percent from Last Year,” October 27, 2026 (U.S. seasonally adjusted purchase-only index up 0.3 percent on the month and 2.4 percent from August 2025 to August 2026; July’s previously reported 0.3 percent change revised to 0.2 percent; nine-division monthly range from −0.8 percent in New England to +2.1 percent in East South Central; twelve-month range from +0.5 percent in Mountain to +4.4 percent in East North Central; next release November 24, 2026), and FHFA purchase-only monthly index levels via FRED series HPIPONM226S and PONHPI00103M226S (U.S. August 444.61, July 443.21, August 2025 434.04; South Atlantic August 467.60, July 467.93, August 2025 461.52). S&P Dow Jones Indices, “S&P Cotality Case-Shiller Index Reports Annual Gain in August 2026,” October 27, 2026 (national NSA +2.1 percent year over year; 10-City +3.6 percent; 20-City +2.7 percent; national NSA −0.2 percent month over month and SA +0.3 percent; Miami +4.24 percent year over year, level 454.69; Tampa −0.39 percent year over year, level 372.60; Chicago +6.7 percent; Seattle −2.0 percent; Detroit August omitted for Wayne County recording delays; CPI year-over-year 3.4 percent cited in the release analysis). Freddie Mac Primary Mortgage Market Survey, October 22, 2026, as already briefed. Census/HUD September housing starts CB26-162 and NAR September existing-home sales only as already briefed on those pages. Board of Governors FOMC calendar for October 27–28.
For help reading these releases against a specific house or still-building lot in Hernando, Citrus, Pasco, Hillsborough, or Pinellas County, contact Bridge Point Business & Real Estate Advisors at 352-515-0226 or request a consultation.
Questions people ask first
Quick answers to common questions about this topic.
What was the September 2026 new-home sales pace?
Census and HUD put sales of new single-family houses at a seasonally adjusted annual rate of 676,000 in September 2026, release CB26-174, published October 27. The revised August rate was 680,000. The September 2025 rate was 714,000. The not-seasonally-adjusted count for the month was 56,000 houses.
Did the sales change clear Census’s confidence interval?
No. The monthly change is 0.6 percent below August with a 90 percent interval of plus or minus 13.8 percent. The year-ago change is 5.3 percent below September 2025 with a plus or minus 12.5 percent interval. Both ranges include zero, so Census does not treat either sales move as statistically significant.
How many new houses were for sale, and what was months’ supply?
The seasonally adjusted for-sale inventory was 476,000 at the end of September, 1.0 percent below August’s revised 481,000. That monthly inventory drop cleared its plus or minus 0.9 percent interval. Months’ supply was 8.4, compared with 8.5 in August and 8.2 in September 2025. Of the 476,000, 111,000 were completed, 250,000 were under construction, and 115,000 were not started.
What did the August 2026 FHFA House Price Index report?
U.S. house prices rose 0.3 percent from July to August 2026 and 2.4 percent from August 2025 to August 2026 on the seasonally adjusted purchase-only House Price Index. FHFA published the release on October 27, 2026. July’s previously reported 0.3 percent U.S. change was revised to 0.2 percent. The U.S. index level was 444.6 in August, with January 1991 equal to 100.
How did the South Atlantic division and Florida’s Case-Shiller metros change?
FHFA’s South Atlantic seasonally adjusted purchase-only index was about 0.1 percent lower from July to August and about 1.3 percent higher from August 2025 to August 2026. Case-Shiller’s Miami metro rose 4.2 percent over the year ending August 2026. Tampa fell 0.4 percent over the same year. Those are division and metro repeat-sales readings, not county medians.
What were the median and average prices of new houses sold in September 2026?
The median sales price was $400,400. The average sales price was $472,800. August’s revised median was $385,400 and August’s revised average was $470,800. September 2025’s median was $416,800 and September 2025’s average was $506,800. The average’s 6.7 percent year-ago decline, plus or minus 6.6 percent, does not include zero.
What did the South region print for new-home sales?
South sales were 413,000 at a seasonally adjusted annual rate, compared with revised August 442,000 and September 2025 416,000. Both the monthly and yearly percent changes have intervals that include zero. Florida is inside the South. The release does not print a Florida or Citrus sales count.
Are new-home sales, the FHFA index, and Case-Shiller the same report?
No. CB26-174 counts new-home contracts. The FHFA purchase-only index measures repeat-sale price change on enterprise purchase mortgages. Case-Shiller is a separate repeat-sales home-price index with national and metro readings. A new house with one sale cannot yet be a repeat sale in either price index.
What mortgage rate applies when reading this tape?
Freddie Mac’s October 22, 2026 survey put the 30-year fixed at 7.32 percent and the 15-year at 6.68 percent. September contracts in the sales file were signed in September. A current lock is a written quote dated after October 22, not the survey average alone.
When are the next related releases?
The October FOMC statement is due October 28, 2026, at 2:00 p.m. Eastern. FHFA’s next HPI report, with data through September and third-quarter figures, is scheduled for November 24, 2026. Census and HUD scheduled the October new-home sales report for November 25, 2026.
Talk with Bridge Point
Considering a purchase or sale in this market? Local guidance can make a meaningful difference.
Schedule a consultation
