
Market Update · 14 min read
White House Order Aims at Mortgage Insurance, Refinance Title Costs, and Factory-Built Homes
On October 22, 2026, the White House ordered FHFA to pursue a mortgage-insurance cancellation pilot at Fannie Mae and Freddie Mac, expand automated title review on eligible refinances, stand up a manufactured-housing task force with recommendations due in 180 days, and direct USDA and VA to reduce rates on their direct single-family loans — steps that matter for Florida buyers, sellers, and owners once agencies implement them.

On October 22, 2026, the President signed an executive order titled Decreasing Housing Costs for the American People. The order directs the Federal Housing Finance Agency to pursue a mortgage-insurance cancellation pilot at Fannie Mae and Freddie Mac, expand automated title review into an ongoing nationwide refinance program, establish a Task Force on Manufactured Housing Innovation with recommendations due within 180 days, and instruct the Secretaries of Agriculture and Veterans Affairs to reduce interest rates on single-family home loans those departments make directly. For a Florida buyer, seller, or owner, the useful read is what the order starts inside the federal housing-finance system — and what still waits on agency procedures, safety-and-soundness findings, and, where the text says so, available appropriations.
The order’s stated policy is to reduce regulatory barriers to mortgage origination and costs that impede homeownership, embrace innovative risk and value assessment technologies, and promote competition and innovation in the housing and mortgage market. It does not rewrite local Florida zoning, set a new Freddie Mac survey average, or print a statewide median sale price. Financing context for the same week sits on Freddie Mac’s October 22 survey, which put the 30-year fixed at 7.32 percent and the 15-year fixed at 6.68 percent. Construction supply context sits on September housing starts. Statewide purchase and sale work sits on residential, and the market map stays on Florida markets.
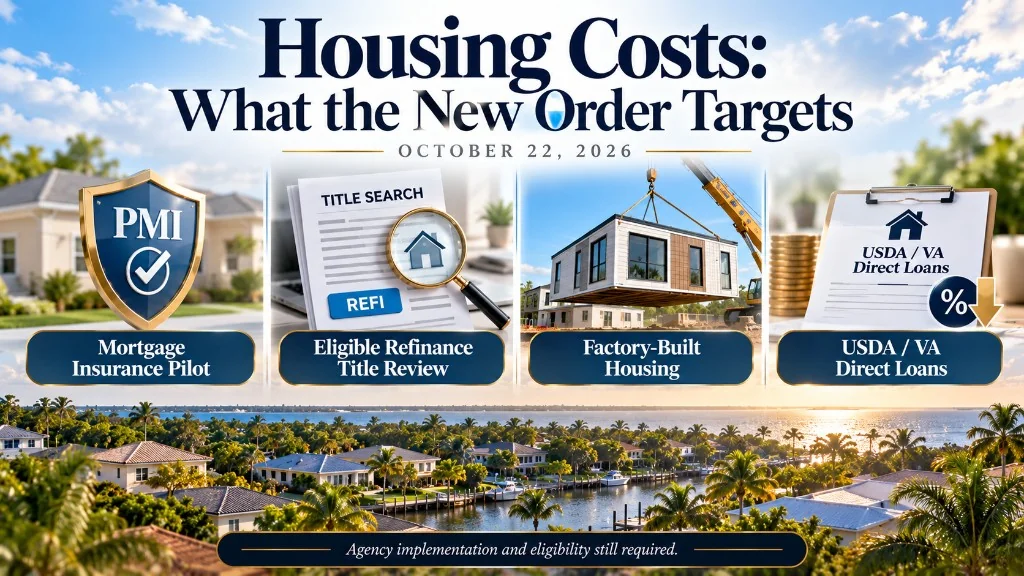
What the order tells FHFA to do on mortgage insurance
Section 2 aims at private mortgage insurance that borrowers carry when equity is thin. The Director of the Federal Housing Finance Agency shall, if he determines it is in the best interests of Fannie Mae and Freddie Mac (the Enterprises), FHFA, and the American public, direct the Enterprises to establish a pilot program. The pilot applies only to mortgages made after the pilot is established. It does not automatically rewrite every existing loan on the books.
Under the pilot, the Enterprises would periodically review single-family loans they own, guarantee, or securitize, using automated valuation models and other available data to assess current market value and identify borrowers who appear to satisfy equity and other requirements for cancellation of mortgage insurance. Cancellation would be proactive when an Enterprise determines that the borrower meets applicable equity requirements based on current market value, that cancellation is consistent with financial safety and soundness and with contractual obligations, and that the borrower meets all other statutory, contractual, regulatory, and Enterprise requirements for cancellation.
The Director shall also direct the Enterprises to require servicers, to the extent permitted by law and operationally feasible, to notify borrowers promptly when mortgage insurance may be canceled under the pilot, and to reduce or eliminate unnecessary documentation requests, appraisal costs, and other administrative barriers to cancellation. For a Florida owner who already carries mortgage insurance on a newer conforming loan, the practical next step is not to assume the premium stops tomorrow. It is to ask the servicer whether the loan will be eligible once the pilot exists, what equity and payment-history standards the Enterprises publish, and whether an automated valuation path is available without a full appraisal.
What the order does on title insurance for refinances
Section 4 focuses on title costs that show up especially on refinances. The Director shall, if he determines it is in the best interests of the Enterprises or FHFA and the American public, and consistent with safety and soundness, his authorities as regulator and conservator, and applicable law, direct the Enterprises to expand the title acceptance pilot into an ongoing program, available nationwide through both Enterprises. Under that program, an Enterprise may accept an automated title review or other title-risk assessment approved by FHFA in lieu of a lender’s title insurance policy on eligible refinance transactions.
In expanding the program, the Director shall consider extending eligibility to refinance transactions with loan-to-value ratios above the current 80 percent limit where title risk remains low; removing geographic limitations and certifying additional title-assessment providers to promote competition; waiving appraisals, income re-verification, and other documentation requirements for limited cash-out refinances that reduce the borrower’s monthly payment, where the Enterprise’s existing data support doing so; and reducing or eliminating loan-level price adjustments and other Enterprise fees on such refinances. The Director shall require that cost savings from the program be passed through to borrowers and that lenders inform borrowers of those savings.
That is a refinance file, not a purchase-file rewrite. A Florida homeowner shopping a rate-and-term or limited cash-out refinance should ask the lender whether the loan will be delivered to Fannie Mae or Freddie Mac under the expanded title-acceptance program, whether the property and LTV fit the eligibility the Enterprises publish, and how any waived appraisal or reduced fee shows up on the Loan Estimate and Closing Disclosure. A purchase borrower still underwrites title the way the contract and the lender require for that transaction. The order’s title section is written around eligible refinances.
Manufactured and factory-built housing: a 180-day task force
Section 3 establishes the Task Force on Manufactured Housing Innovation, co-chaired by the Secretary of Housing and Urban Development and the Director of FHFA, or their designees. Members include the Secretaries of Agriculture, Commerce, and Veterans Affairs, or their designees. The co-chairs may invite other agency heads as appropriate.
Within 180 days of the order, the Task Force shall submit to the President, through the Assistant to the President for Economic Policy, recommendations to facilitate modern manufacturing methods in the production of manufactured and other factory-built housing eligible for Federal housing programs. Those recommendations are to include actions that promote specifications, certifications, inspections, and approvals across Federal housing and housing-finance programs; establish reciprocal recognition among agencies of licenses, certifications, approvals, and inspections where that avoids unnecessary duplication; eliminate Federal requirements and duplicative reviews that unnecessarily impede automation, modularization, standardized production, or other advanced manufacturing techniques, or that increase the time or cost of bringing homes to market; use Federal financing, insurance, guarantee, purchasing, and other program authorities to encourage innovation and increased production of affordable manufactured and factory-built homes; and promote competition among manufacturers and other market participants while maintaining appropriate standards for safety, quality, durability, and consumer protection.
The Task Force shall also evaluate whether, and under what existing statutory authorities, Federal grant funding may be conditioned on, or used to incentivize, State and local adoption of standardized permitting and licensing for manufactured and other factory-built housing, consistent with best practices issued under section 4(a) of Executive Order 14394 of March 13, 2026 (Removing Regulatory Barriers to Affordable Home Construction), and shall prepare legislative recommendations to codify those policies. Agency heads on the Task Force shall, within their authorities, take appropriate action to implement the Task Force’s recommendations.
For a Florida buyer looking at a manufactured or modular product, and for a builder or dealer working that shelf, the order is a federal coordination clock — recommendations within 180 days, then agency implementation and any state or local permitting changes that follow. It does not, by itself, issue a Florida building permit or change a county land-development code overnight. National construction volume remains the separate Census and HUD starts file linked above. County growth patterns, such as Hernando’s ten-year growth briefing, remain the local population and permit story next to any federal manufacturing push.
USDA and VA direct loan rates
Section 5 directs the Secretary of Agriculture and the Secretary of Veterans Affairs, consistent with applicable law — including 42 U.S.C. 1490a(a)(1)(B) and 38 U.S.C. 3762(c)(1) — and available appropriations, to reduce the interest rates charged on single-family home loans made directly by their respective departments. Those are department-direct loan programs, not the weekly Freddie Mac Primary Mortgage Market Survey average and not every VA or USDA guaranteed loan a private lender originates.
A Florida buyer who is shopping a USDA direct loan or a VA direct loan should ask the relevant department office or an approved lender what rate is currently charged on that direct product after the Secretaries act, and should confirm eligibility, property location, and funding availability. The order tells the Secretaries to reduce those direct rates within the statutes and appropriations that govern them. It does not print the new coupons in the White House text.
What changes for Florida buyers, sellers, and owners — and what does not
For a buyer, the order is a cost-of-credit and cost-of-closing agenda aimed at mortgage insurance rules at the Enterprises, refinance title costs, factory-built supply policy, and USDA and VA direct loan rates. It does not replace a written purchase quote, a condo association review, or a local inspection contingency. Resale condo and townhouse pace remains the separate Florida third-quarter condo briefing. Labor-market context for a household deciding whether this is the month to write an offer remains the separate Florida September employment briefing. Ask the lender how Fannie Mae or Freddie Mac delivery, mortgage insurance, and any refinance title path will work on the specific loan program you are using.
For a seller, the order does not set list price, days on market, or a county median. Buyers still arrive with quotes shaped by the current conforming average and by their own credit, down payment, and property type. A listing that assumes every buyer’s mortgage insurance will cancel under a pilot that has not yet been established is getting ahead of the Enterprises’ procedures. Price from comparable closed sales and from the payment a qualified buyer can actually support on a dated rate sheet.
For an owner who already holds a mortgage, the mortgage-insurance pilot matters if the loan is a post-pilot origination that the Enterprises own, guarantee, or securitize and if equity and other requirements are met under the procedures FHFA and the Enterprises publish. The refinance title program matters if you are refinancing into an eligible Enterprise refinance and the lender can use the automated title path. USDA and VA direct-rate reductions matter if your loan is a department-direct product those Secretaries price. None of those paths creates a private right of action against the United States; section 6 of the order states that it does not create any right or benefit enforceable by any party.
What the order does not do in one stroke is equally plain in the text. Implementation is subject to applicable law and available appropriations. FHFA actions tied to the Enterprises rest on determinations about best interests, safety and soundness, and contractual obligations. The manufactured-housing recommendations are due within 180 days; they are not already a finished rulebook. Local permitting for a Florida subdivision still runs through the county or city that issues the permit. The national rate survey, the starts release, and the Florida jobs release remain separate files on this site.
Practical next steps
Start with the loan you have or the loan you are about to apply for. If you carry mortgage insurance, call the servicer and ask whether the loan will fall under the Enterprises’ cancellation pilot once it is established, what equity test will apply, and how notification will work. If you are refinancing, ask the lender whether the expanded title-acceptance program is available on your refinance, whether any appraisal or documentation waiver applies, and how savings appear on the disclosures. If you are shopping USDA or VA direct financing, confirm the current direct rate with the department channel that prices that product. If you are comparing a factory-built or manufactured option, treat the Task Force calendar as a federal policy clock and still read the Florida permit and inspection path for the specific site.
Bridge Point Business & Real Estate Advisors works purchase and sale files across Hernando, Citrus, Pasco, Hillsborough, Pinellas, and by assignment elsewhere in Florida. For help reading this federal order against a specific house, refinance, or listing strategy, call 352-515-0226 or request a consultation. Mortgage questions are routed to licensed lenders; Bridge Point is a brokerage, not a lender.
Source: The White House, *Decreasing Housing Costs for the American People*, presidential action dated October 22, 2026.
Questions people ask first
Quick answers to common questions about this topic.
When was the Decreasing Housing Costs for the American People order signed?
The White House presidential action is dated October 22, 2026. It directs FHFA, HUD, USDA, Commerce, VA, and related agencies on mortgage insurance, refinance title acceptance, manufactured housing, and USDA and VA direct loan rates.
Does the order immediately cancel mortgage insurance on every Florida loan?
No. Section 2 directs FHFA, if the Director makes the required determinations, to have Fannie Mae and Freddie Mac establish a pilot that applies only to mortgages made after the pilot is established. Cancellation still requires equity, safety-and-soundness, contractual, and other Enterprise requirements, with servicer notice where permitted and feasible.
What changes for refinance title insurance under the order?
Section 4 directs FHFA, subject to the Director’s determinations and applicable law, to expand the title acceptance pilot into an ongoing nationwide program at both Enterprises. An Enterprise may accept an FHFA-approved automated title review or other title-risk assessment in lieu of a lender’s title insurance policy on eligible refinance transactions, with cost savings required to be passed through to borrowers.
How soon must the manufactured-housing task force report?
Within 180 days of the order, the Task Force on Manufactured Housing Innovation — co-chaired by HUD and FHFA and including Agriculture, Commerce, and Veterans Affairs — shall submit recommendations on factory-built and manufactured housing eligible for Federal housing programs.
What did the order say about USDA and VA loan rates?
Section 5 directs the Secretaries of Agriculture and Veterans Affairs, consistent with applicable law including 42 U.S.C. 1490a(a)(1)(B) and 38 U.S.C. 3762(c)(1) and available appropriations, to reduce interest rates on single-family home loans made directly by their departments.
Does this order change Florida’s local building permits or Freddie Mac’s weekly rate survey?
No. The order is a federal executive action aimed at Enterprise pilots and programs, a manufactured-housing task force, and USDA and VA direct loan pricing. Local Florida permits still follow local authorities. Freddie Mac’s Primary Mortgage Market Survey remains a separate weekly average — 7.32 percent on the 30-year for the week ending October 22, 2026, on this site’s briefing.
What should a Florida buyer or owner do next?
Talk with your lender or servicer about whether your loan fits the coming mortgage-insurance pilot or the expanded refinance title program, and confirm USDA or VA direct rates if that is your product. For purchase or sale strategy in Hernando, Citrus, Pasco, Hillsborough, Pinellas, or by assignment elsewhere in Florida, call Bridge Point at 352-515-0226 or use /contact.
Talk with Bridge Point
Considering a purchase or sale in this market? Local guidance can make a meaningful difference.
Schedule a consultation
