Buyer & Seller Guide · 13 min read
Buying or Selling a Florida Home With Solar Panels: What Happens to the Loan or Lease
Selling a house with solar panels in Florida starts with three questions: who owns the equipment, what obligations remain, and what must happen before the buyer takes over? A solar loan, an equipment lease, and a system owned without separate debt can lead to different closing arrangements. The executed agreements, current account records, and required approvals answer those questions, not the panels on the roof.
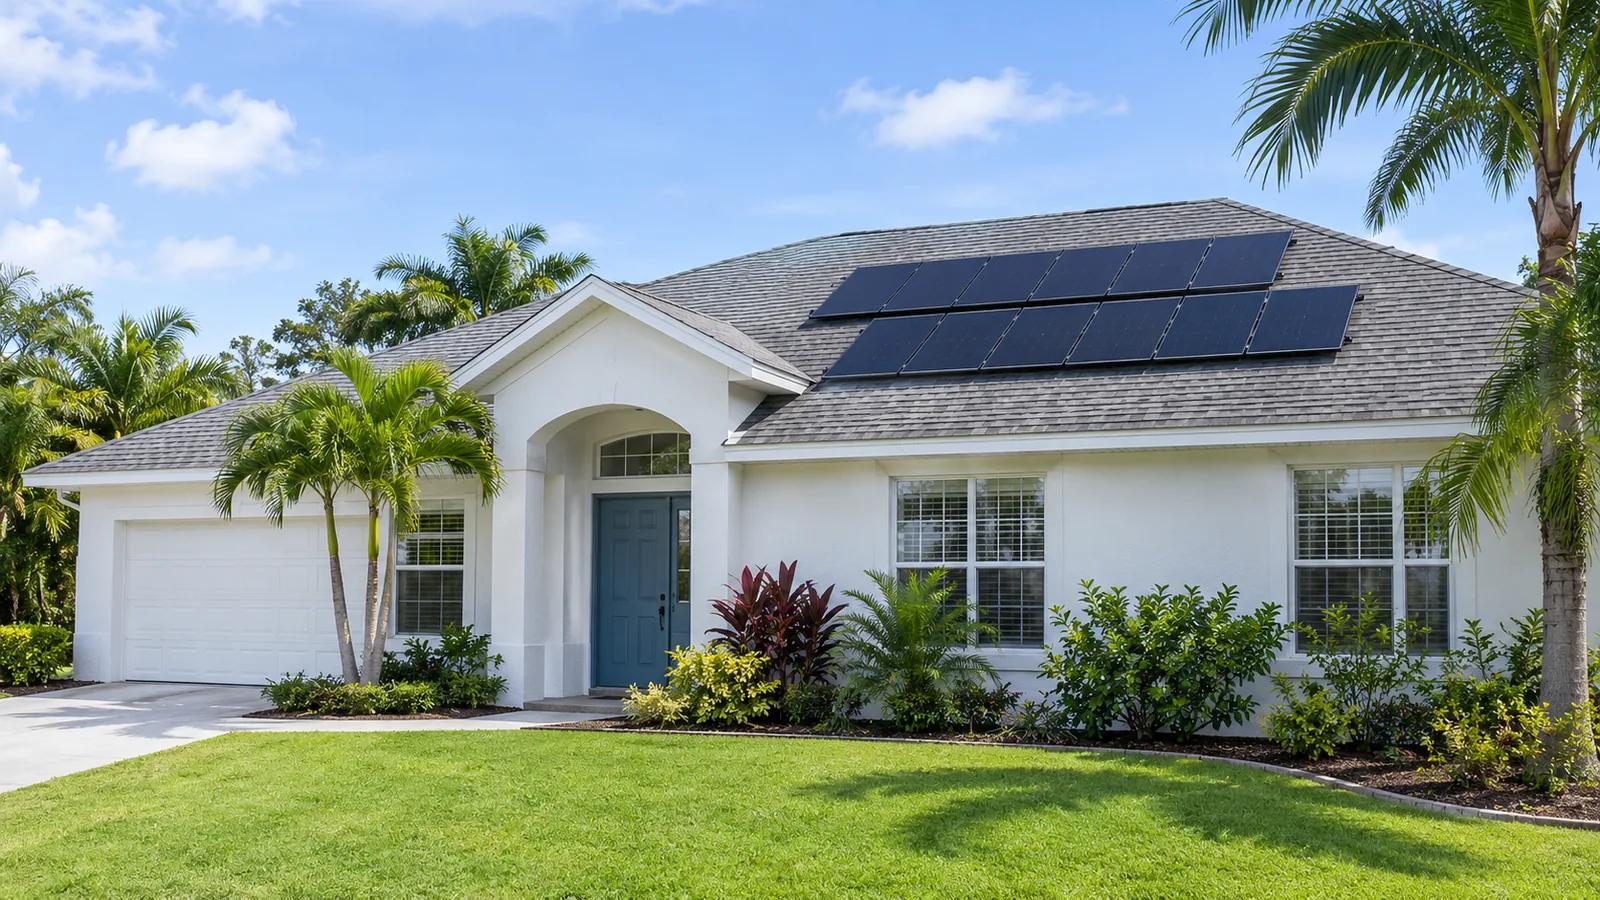
Selling a house with solar panels in Florida starts with three questions: who owns the equipment, what obligations remain, and what must happen before the buyer takes over? A solar loan, an equipment lease, and a system owned without separate debt can lead to different closing arrangements. The panels on the roof do not answer those questions. The executed agreements, current account records, and required approvals do.
For a buyer, the goal is to understand the house and the solar arrangement together before making a binding commitment to unfamiliar payments. For a seller, early document collection helps explain what is included and identify whether payoff, an approved transfer, or another negotiated solution is workable.
In Hernando and Pasco counties, organize that review alongside the roof inspection, insurance quote, mortgage application, and closing work. A solar provider's transfer process should have its own place on the transaction calendar. Do not leave it as an assumed administrative step after the purchase contract is signed. The broader steps are on residential selling and residential buying; this guide covers what changes when the house has a solar system.
Start with ownership and the actual agreement
Find the original installation agreement, any financing or lease documents, amendments, and current statements. Florida's distributed energy generation disclosure statute requires applicable sale or lease agreements to include a separate acknowledged disclosure addressing matters such as purchased versus leased status, costs, payments, financing, savings assumptions, and specified fees. Request the original disclosure as part of the file; it does not replace the financing agreement. [1]
Read the names carefully. The installer, equipment manufacturer, loan servicer, equipment owner, and monitoring company may appear in different documents. Make a contact sheet showing which organization answers each question. Ask for written confirmation when a company says another business now administers the account.
Use this comparison to identify the next document to request. These are review categories, not conclusions about a particular property's title or mortgage eligibility.
| Arrangement | What to establish | Main sale question |
|---|---|---|
| Owned without separate solar debt | Ownership evidence and any remaining service commitments | What equipment and transferable benefits are included? |
| Purchased with a solar loan | Note, security agreement, balance, and transfer restrictions | Will the debt be paid off or can an approved assumption occur? |
| Equipment lease | Third-party ownership and the complete lease | Will the provider approve assignment or offer a contractual buyout? |
| PACE-financed improvement | Assessment agreement and outstanding obligation | What disclosure, lender review, and payoff arrangements apply? |
A lease generally means the household uses equipment owned by another party. It is different from borrowing money to purchase equipment. The FTC also distinguishes an equipment lease from a power purchase agreement, under which the customer purchases generated electricity. Its national discussion does not establish which arrangements are lawful for a particular Florida property. [2]
Avoid describing panels as paid off solely because there is no payment on the seller's current bank statement. A prepaid lease, a payment made through another account, or an assessment collected with taxes needs its own explanation. Ask what document will establish the ownership and obligations the buyer receives.
Treat Florida power purchase agreements as a separate legal question
Do not assume a solar arrangement offered elsewhere is available on identical terms in Florida. The Florida Public Service Commission's Sunrun declaratory order addressed a specific equipment lease with payments independent of electricity production. The decision distinguished that arrangement from selling electricity and limited its review to the facts presented. It is not blanket approval of every contract labeled a lease or PPA. [3]
Florida's statutory public utility definition includes entities supplying electricity to or for the public, subject to its terms and exclusions. If a proposed agreement charges for electricity output or is described as a PPA, have Florida counsel and the serving utility confirm the applicable arrangement. A national financing guide's discussion of PPAs is not a Florida regulatory determination. [4]
For the transaction file, ask the provider to identify exactly what the buyer would purchase: equipment, the right to use equipment, maintenance, or electricity. That answer should agree with the contract's payment formula and ownership provisions.
Assemble one solar document package
The most useful package connects the physical system to the legal and financial records. A promotional proposal alone cannot do that. Label documents by date and preserve the executed version when a salesperson also provided an earlier estimate.
| Document group | Questions to resolve | Who should review |
|---|---|---|
| Installation and ownership records | Which panels, inverter, batteries, and accessories are included? | Buyer, seller, and qualified solar professional |
| Loan or lease file | What remains payable and what transfer or buyout terms apply? | Provider, lender, and attorney as needed |
| Payoff and filing records | What must be released, terminated, or subordinated? | Closing professional and mortgage lender |
| Permits and completion records | Do the records match the installed system and later alterations? | Building department and qualified contractor |
| Roof and warranty documents | What transfers and who handles removal or reinstallation? | Roofer, solar provider, and warranty issuers |
| Utility and production records | What approval and account changes will the buyer need? | Serving utility and system provider |
| Insurance documents | What property and liability coverage is required or available? | Insurance agent and mortgage lender |
Add recent statements and correspondence about disputes, outages, damage, service claims, or missed payments. An unanswered service ticket belongs in the review even when the system is producing electricity today. Ask whether the sale changes access to a monitoring platform or the person authorized to request repairs.
Buyers should receive enough time to evaluate the actual documents under their purchase agreement. If a major agreement is missing, identify who will obtain it and by when. A vague statement that documents will arrive before closing leaves little room to address an unexpected obligation.
Separate loan payoff from loan assumption
If the seller financed the purchase, ask the finance provider for the note, current payment schedule, payoff procedure, and any conditions governing a sale. The CFPB has documented solar loans with pricing markups and payment structures that change unless a substantial prepayment occurs. An old advertised payment is therefore a poor substitute for the current agreement and statement. [5]
A payoff review should answer how much is required through the expected closing date, whether the quote expires, how funds must be delivered, and what evidence follows payment. Let the closing professional verify payment instructions through an established process. Ask who obtains the release of any associated filing and how its completion will be documented. Bridge Point's affiliated title company, Time to Close Title, handles settlement statements for residential closings.
If the parties prefer assumption, start by asking whether the particular lender permits it. Request the application, approval conditions, fees, processing steps, and written treatment of the seller's continuing liability. The buyer should also send the proposed obligation to the mortgage lender. Agreement between buyer and seller alone does not establish that a third party has approved the arrangement.
Consider an illustrative negotiation: a seller offers to leave the solar debt in place because its monthly payment seems manageable. The buyer is willing in principle but has not seen the transfer provisions. The next step is to obtain the provider's written options and the mortgage lender's response, then negotiate an option both can actually carry out. An attractive payment does not resolve authority to transfer it.
If payoff is the agreed route, include it in the seller's proceeds planning. If assumption remains conditional, ask the contract professionals to address the approval deadline and what happens if it fails; how the buyer's deposit is held while a condition is pending is explained in what earnest money is and how it works in Florida. A price concession alone does not complete either process, and a credit and a price cut affect the buyer differently, as shown in seller credit versus price reduction in Florida.
Read lease assignment and buyout terms separately
For a leased system, ask the owner or authorized administrator to provide the complete assignment package. Review the remaining term, payment changes, maintenance obligations, transfer charges, credit review, default provisions, and end-of-term options. Ask whether the buyer must accept the existing agreement or sign new documents.
Keep a lease buyout distinct from paying the remaining installments. Request a written statement explaining whether a proposed payment purchases the equipment, prepays use of it, terminates obligations, or accomplishes something else. The documents should identify who owns the equipment afterward and what service commitments survive.
The seller should seek written confirmation of release from future obligations if that is part of the negotiated transaction. The buyer should identify any new responsibilities and the date they begin. Preserve the provider's approval and the final signed transfer documents with the closing file.
If you are buying a home with leased solar panels, make sure you can explain the agreement without relying on the seller's summary. What is the payment next year? Who answers a repair call? What happens during roof replacement? What choices exist when the term ends? Unclear answers are reasons to obtain clarification before the relevant contractual deadline.
Give the mortgage lender and closing team the same facts
Fannie Mae's current guidance distinguishes owned, separately financed, and leased panels. It requires lenders to determine ownership and financing and review relevant records. Its treatment of appraisal value, borrower obligations, and title depends on that structure; leased panels are not included in appraised property value under its policy. This is one financing framework, not a promise of approval for every loan. Buyers who need a lender introduction can start on the mortgage page. [6]
A Uniform Commercial Code filing also needs interpretation. Fannie Mae distinguishes personal property security interests, fixture filings, and precautionary filings connected to third-party ownership. Do not describe every UCC filing as a lien on the entire house or assume a real estate title search answers every equipment ownership question. Send the actual documents to the closing professional and lender. [6]
The original installation price, remaining balance, and any contribution to market value are separate figures. Ask the agent how the proposed price compares with relevant properties, and provide accurate ownership information for the appraisal process. Bridge Point's Florida appraisal changes guide provides context on the appraisal report and property documentation, and the general pricing method is in pricing strategy when selling your Florida home. When an independent opinion of value matters, Bridge Point's certified appraisers can prepare one separate from the listing conversation. [7]
Identify PACE assessments early
PACE financing should be reviewed separately from an ordinary solar loan or equipment lease. Under Florida's current residential qualifying improvement statute, the assessment is collected with property taxes and creates a property lien. The statute also requires a specified written disclosure at or before the seller executes a sale contract when an assessment under that section has an unpaid balance. [8]
Obtain the financing agreement, assessment schedule, current balance, tax records, and any payoff statement. Ask the closing professional to reconcile these records rather than infer the remaining obligation from one annual tax bill. A buyer needs to understand both the recurring assessment and the amount required if payoff is necessary.
Fannie Mae's dedicated PACE guidance generally excludes mortgages on properties with outstanding PACE obligations that have priority over the first mortgage, while addressing arrangements without that priority separately. Have the buyer's lender determine the applicable requirement; do not advertise automatic transfer simply because an assessment is connected to the property. [9]
Put the lender's answer into the transaction plan before agreeing on net proceeds or cash needed to close. If a document describes an assessment using a program name rather than PACE, still ask what legal obligation it creates.
Review the roof, the system, and the insurance together
The Department of Energy identifies roof condition, age, shape, and shading as relevant to solar suitability. For an existing installation, use that as a starting point for questions about the remaining roof life and the work a future replacement might involve. [10]
Ask a qualified roofer and solar professional to coordinate their observations. Request a written scope for any proposed panel removal and reinstallation, including who disconnects equipment, who protects it during storage, and who restores operation. Clarify whether the provider must approve the contractor and whether the work affects a roof, equipment, or workmanship warranty.
Separate each warranty by issuer, coverage, remaining period, transfer process, and exclusions. A panel manufacturer's promise is not the same document as an installer's workmanship warranty. Florida's solar disclosure requirements specifically address roof warranties and warn that replacing a roof may require reinstalling the system. [1]
Request installation permits, completion records, and documents for later battery or panel changes from the authority responsible for the address. Ask the qualified inspector to state what the inspection covers, what was inaccessible, and whether specialist follow-up is needed. A visual observation of panels does not answer a contract ownership question.
Give the insurance agent the equipment details, ownership arrangement, roof information, and any provider insurance requirements. Ask for written answers about coverage, limits, deductibles, and liability requirements. If the provider insures leased equipment, clarify what that means for the house and the owner's responsibilities instead of assuming the two policies cover identical risks. Flood zone and flood coverage questions for the same house are covered in the Hernando County and Pasco County flood-zone guides.
Confirm utility arrangements and realistic ownership costs
Identify the serving utility from the property account, then ask for its procedure for a new owner of an existing system. For example, FPL instructs a new occupant with existing solar to apply for net metering and sign an interconnection agreement. That is an FPL process; use the actual provider's current requirements for a Hernando or Pasco property. [11]
Ask what happens to the seller's account credits, whether existing approvals remain usable, and whether equipment changes trigger additional review. Coordinate the account transition with possession. Confirm who will answer a utility request if it arrives after the seller moves.
Request a full year of available utility bills and separate production records. FPL explains that electricity generated and consumed within the home does not pass through its meter, so its bill does not show total system production. The production record and utility bill answer different questions. [11]
Build the buyer's budget using the actual loan or lease obligation, remaining utility charges, insurance quote, and expected maintenance responsibilities. Add a separate allowance for identified upcoming work. Compare bills alongside the seller's occupancy and major electricity uses, then discuss how the buyer's plans differ. A household adding an electric vehicle or changing pool equipment should not treat the seller's bill as its own forecast.
Update old tax credit assumptions
Current IRS instructions state that residential clean energy credits cannot be claimed for expenditures made after December 31, 2025. Older proposals describing future federal benefits therefore need current tax review. Do not build a 2026 purchase decision around an installation incentive described in an outdated sales presentation. [12]
A buyer should not assume the seller's previous credit becomes an asset transferred with the home. Have a tax adviser address any remaining tax questions, including prior expenditures or carryforwards. Keep that analysis separate from the provider's payoff figure and the purchase price negotiation.
Put the agreed solar outcome into the closing plan
Before listing, collect the documents and identify available payoff or transfer routes. Before committing to the transaction's deadlines, let the buyer's lender, insurance agent, and closing professional review the arrangement. Before closing, reconcile the agreed route with the provider's final documents and the closing statement.
Create a brief responsibility list showing each outstanding item, the person handling it, and the needed completion date. Include monitoring access, warranty registration, service contacts, utility paperwork, and copies of final approvals in the ownership handover. If a material item remains unresolved, ask the appropriate professional how it affects the contract and closing instead of relying on an informal promise. If the house is also rented, the lease, showing, and deposit handover runs alongside the solar items; those steps are in how to sell a tenant-occupied house in Florida. A seller who is also buying the next house has a second calendar to line up, covered in how to buy and sell a home at the same time in Florida.
Bridge Point's home selling services and home buying services support pricing, offers, negotiation, and transaction coordination. [13][14] Call Bridge Point Business & Real Estate Advisors at 352-515-0226, email info@BridgePointBREA.com, or contact Bridge Point to discuss the house, solar documents, and proposed timeline before marketing or making an offer. [15]
*This guide provides general transaction planning information as of November 8, 2026. It is not legal, tax, or lending advice. Have the appropriate legal, tax, lending, insurance, and technical professionals review the actual agreements and property.*
Sources and further reading
Prepared November 8, 2026.
[1] Section 520.23, Florida Statutes (2026) — Disclosures required
[2] Federal Trade Commission — Solar Power for Your Home
[4] Section 366.02, Florida Statutes (2026) — Definitions
[5] Consumer Financial Protection Bureau — Issue Spotlight: Solar Financing
[6] Fannie Mae Selling Guide B2-3-04 — Special Property Eligibility Considerations (November 4, 2026)
[7] Bridge Point — Florida Appraisal Changes in 2026: The New UAD 3.6 Report
[8] Section 163.081, Florida Statutes (2026) — Financing qualifying improvements to residential property
[9] Fannie Mae Selling Guide B5-3.4-01 — Property Assessed Clean Energy Loans (October 8, 2025)
[10] U.S. Department of Energy — Homeowner's Guide to Solar
[11] FPL — Net Metering Frequently Asked Questions
[12] IRS — Instructions for Form 5695 (2025), Residential Energy Credits
[13] Bridge Point — Selling Residential Real Estate in Florida
[14] Bridge Point — Buying Residential Real Estate in Florida
Questions people ask first
Quick answers to common questions about this topic.
Can I sell a Florida house if I still owe money on the solar panels?
Yes, but the balance has to be resolved as part of the transaction. Start by obtaining the loan documents, current payoff information, and any permitted assumption process. Have the closing professional and the buyer's lender evaluate the proposed arrangement. Neither payoff nor transfer should be assumed from the listing description.
Does the buyer automatically take over the solar loan?
No. Do not assume an automatic transfer. Ask the finance provider whether assumption is available, what approval is required, and whether the seller would be released. Put the approved arrangement and deadlines into the transaction documents with the appropriate professional's help.
What should I check before buying a home with leased solar panels?
Review ownership, remaining term, payments, assignment approval, maintenance, roof work, and end-of-term options. Obtain the provider's written transfer requirements and ask your mortgage lender to review the lease. A summary of the current monthly payment is not enough.
Is a solar power purchase agreement the same as an equipment lease?
No. They describe different arrangements: a lease pays for use of equipment, while a power purchase agreement pays for generated electricity. Florida regulatory treatment needs specific review; the Florida PSC's Sunrun decision addressed equipment payments independent of electricity production. Do not assume a national PPA template has the same status for a Florida home.
Does a UCC filing mean the solar company has a lien on the whole house?
Not necessarily. Personal property, fixture, and precautionary filings can have different significance. Have the closing professional and lender examine the actual filing, collateral description, ownership, and any required release or subordination.
Can a PACE assessment remain after a Florida home is sold?
Do not assume either automatic payoff or automatic acceptance. Florida requires a specified sale disclosure for an unpaid assessment under section 163.081, and mortgage eligibility requires separate review by the buyer's lender. Obtain the assessment documents and the lender's decision before fixing the closing arrangement.
Will solar panels eliminate my electric bill?
Do not count on it. Build the budget from the serving utility's current terms and the property's records, including remaining utility charges, system payments, maintenance, and insurance. The seller's electricity usage and production history help frame questions but do not guarantee the buyer's future costs.
Can I count on a federal solar tax credit when buying the house in 2026?
No. Current IRS instructions for Form 5695 say the residential clean energy credit cannot be claimed for expenditures made after December 31, 2025. Ask a tax adviser about the actual transaction and any separate prior-year issues, and do not treat the seller's credit as automatically transferred.
Who can help buy or sell a home with solar panels in Hernando or Pasco County?
Bridge Point Business & Real Estate Advisors handles residential purchases and sales across Hernando, Pasco, Citrus, Hillsborough, and Pinellas. Call 352-515-0226 and bring the solar installation agreement, loan or lease documents, and current statements to the first conversation.
Talk with Bridge Point
Considering a purchase or sale in this market? Local guidance can make a meaningful difference.
Schedule a consultation